Tesla has reported its Q1 2026 earnings, and the results came in well ahead of Wall Street expectations, delivering a strong start to the year despite lingering concerns around EV demand.
The company posted revenue of $22.4 billion, comfortably beating consensus estimates of $21.4 billion. Profitability also surprised to the upside, with non-GAAP earnings per share of $0.41, well above the expected $0.33.
Perhaps more notably, Tesla delivered a significant improvement in profitability metrics. Gross margin came in at 21.1%, far exceeding expectations of 17.5%, pointing to stronger cost control and a more favourable product mix than analysts had anticipated.
On the bottom line, GAAP net income reached $1.45 billion, also beating estimates of $1.17 billion. Meanwhile, free cash flow came in at $1.44 billion, a sharp reversal from forecasts that had called for a negative $1.57 billion figure.
Automotive stabilizing, global demand improving
While Tesla’s automotive business has faced pressure in recent quarters, the company pointed to improving demand trends globally. According to its shareholder update, demand rebounded in North America and Europe (EMEA), while continuing to grow in Asia-Pacific (APAC) and South America.
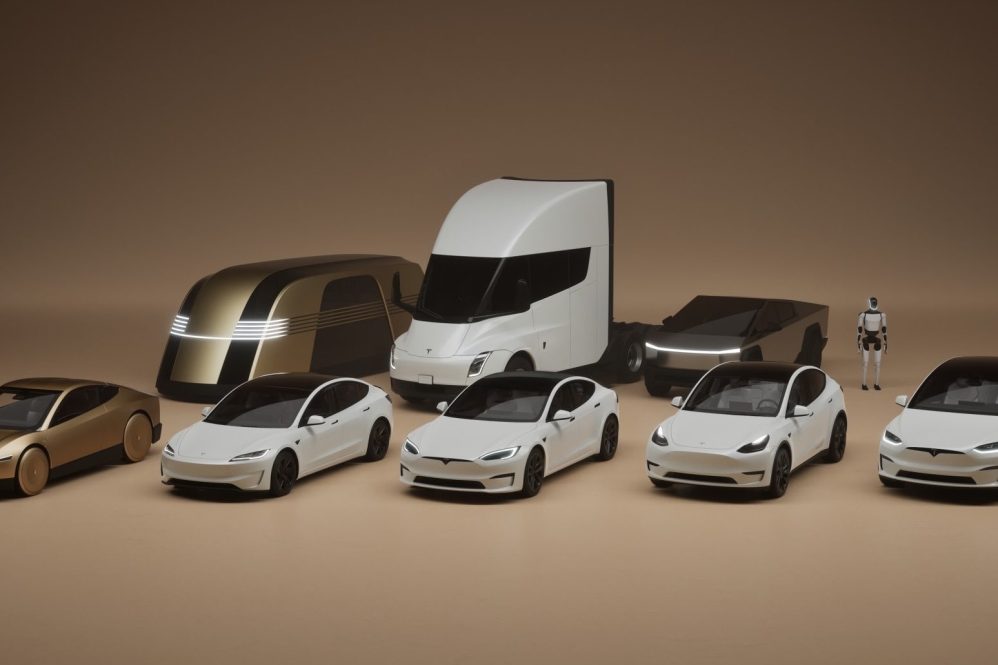
Tesla also highlighted ongoing changes to its lineup, including more affordable variants of the Model 3 and Model Y, along with the expansion of the Model Y L into markets outside China. The company reiterated plans to begin volume production of the Cybercab and Tesla Semi later this year.
Energy declines
Tesla’s energy business, which has been a key growth driver over the past year, showed a slight pullback in Q1. Revenue from energy generation and storage came in at $2.41 billion, down from $2.73 billion in the same quarter last year. The decline appears to be largely tied to the timing of large-scale Megapack deployments, which can fluctuate from quarter to quarter, rather than any change in underlying demand.
Despite the dip, the energy segment remains one of Tesla’s most important profit contributors. The business continues to deliver significantly higher margins than automotive, driven by strong demand for utility-scale storage projects. With new a Megafactory coming online soon in Houston and Megapack 3 production on the horizon, Tesla’s energy division is still expected to play a growing role in both revenue and profitability through the rest of 2026.
Bigger picture
Despite a quarter that was expected to highlight weakness, Tesla instead delivered a strong beat across nearly every key metric. While questions remain around long-term EV demand and the company’s aggressive spending plans, Q1 results suggest Tesla is navigating the transition more effectively than many had anticipated.
Tesla (TSLA) shares are up nearly 4% in after-hours trading following the release of the report.


Always get the latest - make Drive Tesla your preferred source on Google
Are you buying a Tesla? If you enjoy our content and we helped in your decision, use our referral link to get three months of Full Self-Driving (FSD).Drive Tesla uses affiliate links, which means we may earn a commission if you make a purchase through them, at no additional cost to you. Thank you for your support.